Insurance Claim Assistance for Mold Damage Near Me
Starting price: Call for pricing
Most mold claims are denied or cut down over one question: what caused it? Capital Restoration Services documents the moisture source, ties the growth to a covered event, and builds the inspection report your adjuster needs to see. Call (877) 276-1067 before you clean anything — the evidence matters.
Why mold claims succeed or fail on a single word: cause
Insurers rarely argue about whether mold is present. They argue about why it is there. A pipe that burst last Tuesday is a sudden, accidental event — the kind policies are built for. A drip that ran for two years under a sink is a maintenance issue — the kind policies exclude. Both produce mold. Only one produces a covered claim.
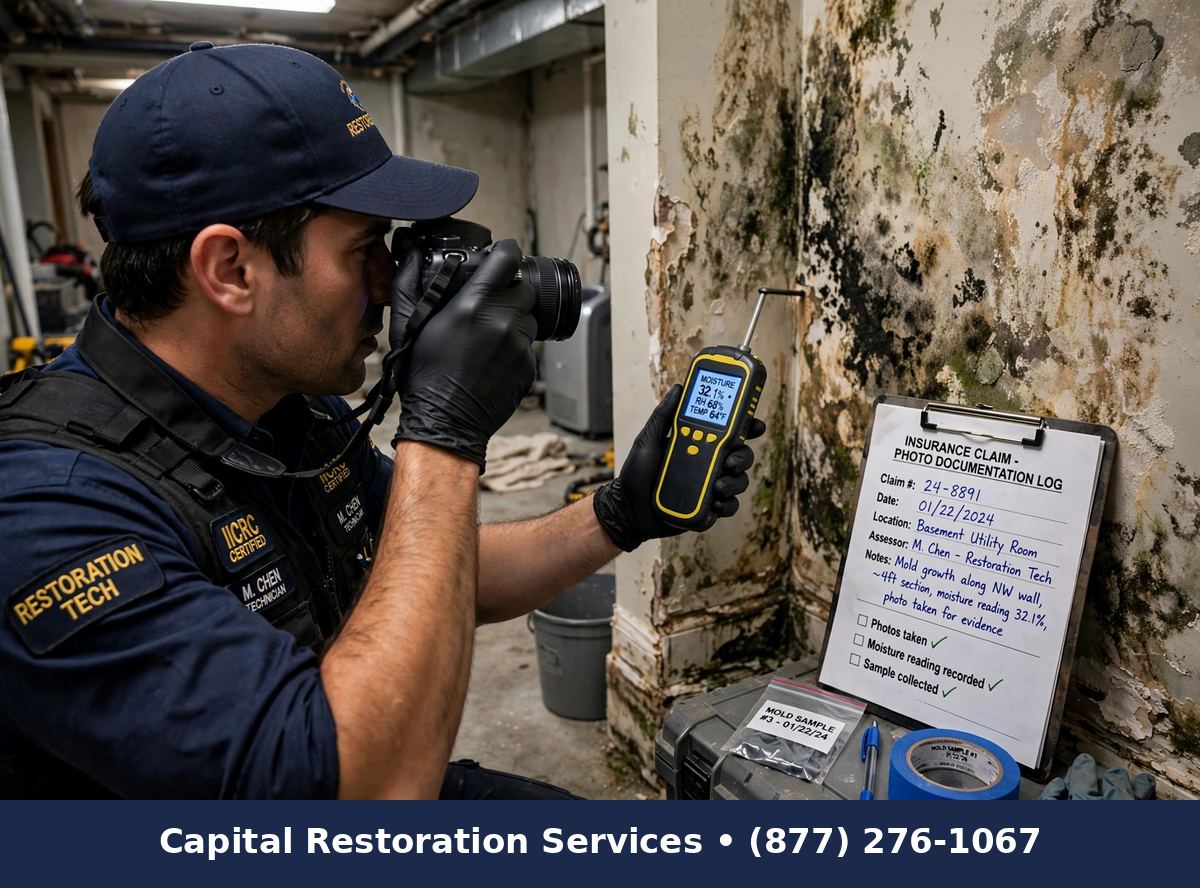
That distinction is why documentation has to start before cleanup. Once the mold is scrubbed and the leak is fixed, the story of what caused what becomes much harder to prove. We inspect first, determine the cause in writing, and photograph the source alongside the growth — so the file shows the connection while it is still visible.
The coverage reality most homeowners discover too late
Even covered mold claims come with a catch: the mold sublimit. Many standard homeowners policies cap mold payouts at a fraction of the overall policy limit — commonly just a few thousand dollars per occurrence — no matter how large the remediation actually is. Some policies offer an endorsement that raises the cap, but you have to buy it before the mold exists.
This is worth knowing before the adjuster arrives. A remediation that legitimately requires containment, HEPA filtration, and material removal can exceed a low sublimit quickly. We read your declarations page with you and shape the scope around what the policy will actually fund, so you are never guessing.
What a claim-ready mold file contains
Adjusters decide mold claims on paper, so the paper has to be good. A strong file has dated photos of the growth and the moisture source, taken before anything is disturbed. It has a written inspection report with a cause determination — our inspector's professional opinion on what water event fed the mold and when. It has test results showing where the contamination reaches, not just where it is visible.
Then come the supporting pieces: plumber invoices or storm reports proving the sudden event, contractor estimates for the remediation, receipts for any emergency mitigation, and a timeline of discovery. Each piece answers a question the insurer will ask. Together they make the claim hard to dismiss.
The exclusions that sink most claims
It helps to know what you are up against. Standard policies typically exclude mold from flooding (that needs separate flood coverage), from sewer or drain backup without an endorsement, from chronic humidity and condensation, and from construction defects. Delayed reporting after discovery is another common reason for denial — finding mold and waiting months to report it reads as neglect.
None of this means a denied-looking situation is hopeless. A storm-torn roof that let rain in is a different claim than a roof that leaked for years. The facts, documented early and honestly, decide which one you have.
What affects your out-of-pocket cost
Three things shape what you pay: your deductible, your mold sublimit, and depreciation on the materials being replaced. The sublimit surprises people most — a homeowner expecting full coverage can discover the policy only funds part of the remediation. Contents damaged by mold may also settle at depreciated value.
What keeps your costs predictable is an honest scope written before work starts, matched to the coverage you actually have. We will not write a plan your policy cannot support. Call (877) 276-1067 and we will go through your numbers together, in plain language.
Serving homeowners across the area
Capital Restoration Services prepares mold claim files for single-family homes, condos, townhouses, and rental properties — the same discipline whether the growth is behind one bathroom wall or through a whole basement. If you have already found mold, do not disturb it yet: photograph it, note the date, and call (877) 276-1067. The file we build in the first days is the file your claim stands on.
Features
- Licensed mold inspection with a written cause determination
- Moisture source tracing — finding the leak or event behind the growth
- Air quality and surface testing results for the claim file
- Dated photos and a discovery timeline organized for the adjuster
- Itemized remediation scope matched to industry practice
- Direct communication with your adjuster on technical questions
- Supplemental documentation if more growth is found during remediation
Benefits
- A documented cause that ties the mold to a covered event, not neglect
- An inspection report written for an adjuster's eyes, not just yours
- Photos, test results, and a timeline organized into one claim file
- Guidance on what your policy's mold sublimit means for your job
- Faster answers from the carrier because the file is complete
- One team handling the inspection, the remediation, and the paperwork
Frequently asked questions
Does homeowners insurance cover mold?
When the mold comes from a covered, sudden event — a burst pipe, an appliance failure, storm damage — most policies respond. When it comes from slow leaks, poor ventilation, or long-deferred maintenance, they usually don't. The deciding factor is almost always the documented cause.
Is there a limit on how much insurance pays for mold?
Very often, yes, in the form of a mold sublimit. Many standard policies cap mold payouts far below the total policy limit — sometimes just a few thousand dollars per occurrence — and some policies add endorsements that raise it. We check what your declarations page says and plan the job around it.
What documentation makes a mold claim stronger?
Photograph the growth and the water source before anything is disturbed. Keep repair invoices, plumber receipts, and storm reports that prove the sudden event. Save our inspection report with its cause determination, plus any test results and contractor estimates. Date everything.
What if the mold came from a leak I didn't know about?
Mold after a slow drip under a sink is the classic denial — insurers read it as a maintenance issue. But a slow leak you genuinely didn't know about is different from one you ignored, and documentation of discovery dates matters. We document honestly and let the file speak.
What will I pay out of pocket on a mold claim?
It comes down to your deductible, your mold sublimit, and whether depreciation applies to the damaged materials. Many homeowners are surprised by how low the mold cap is. We walk through the math with you in plain terms — call (877) 276-1067 and we'll look at your situation together.
Do I need a professional inspection for the claim, or are my photos enough?
A licensed mold inspection with a written cause determination carries the most weight, followed by test results showing the extent of the problem. Contractor estimates round out the file. We provide all three.